
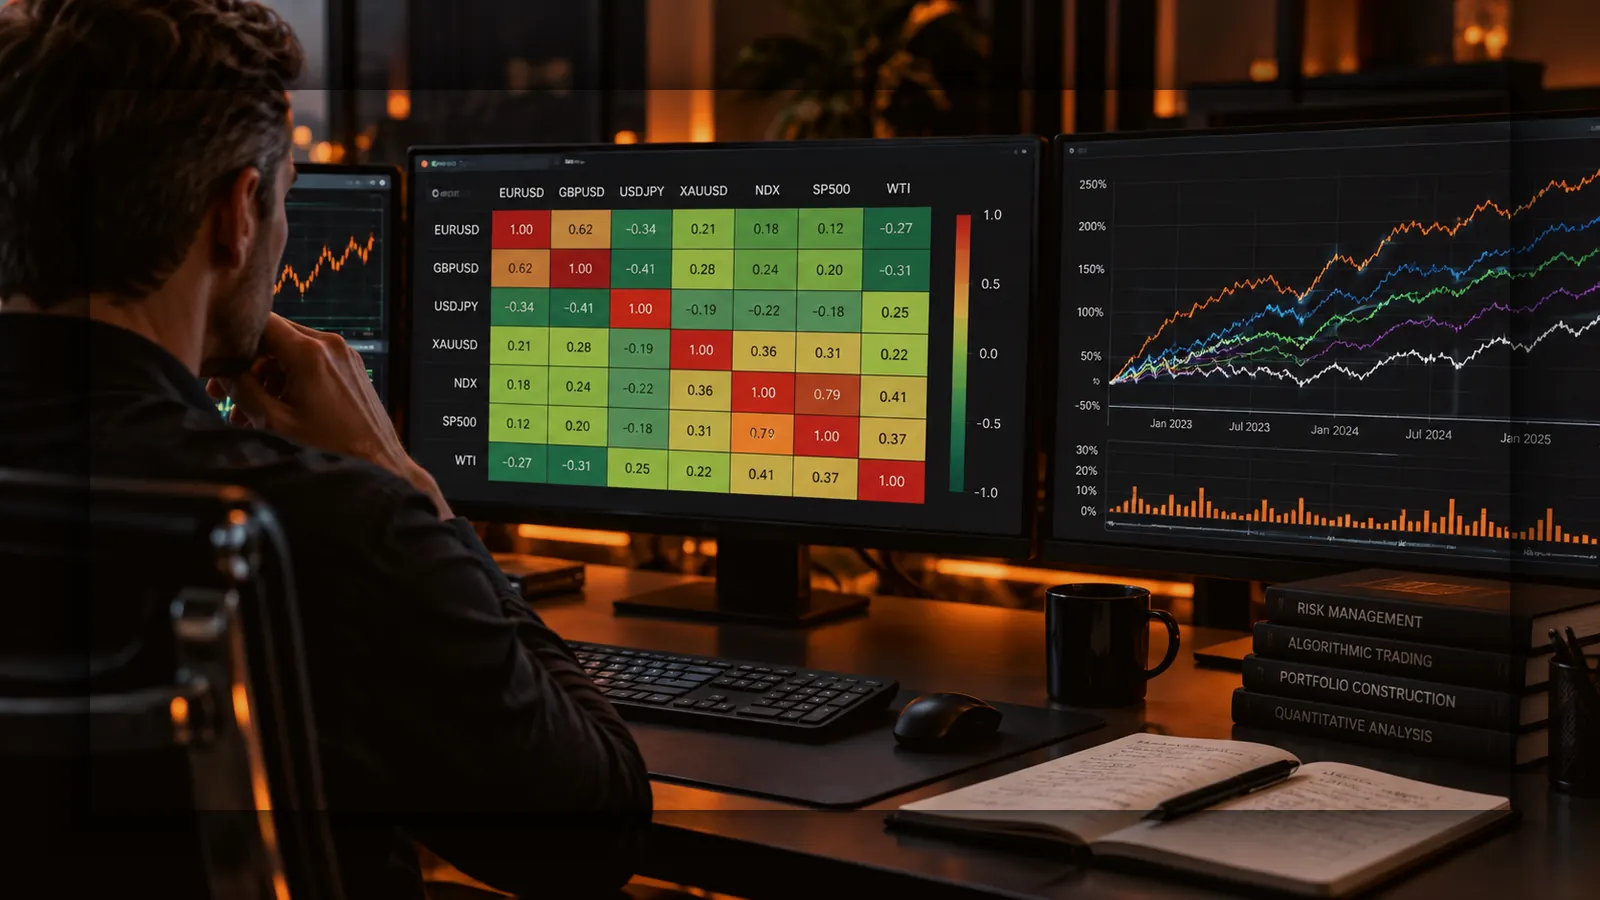
Correlation is one of the most frequently cited numbers in portfolio construction, and one of the most frequently misread. A low correlation figure between two strategies is genuinely useful information. It is not, on its own, proof of diversification, and it is not a guarantee of anything about the future. Understanding what correlation actually measures — and what it quietly leaves out — makes it a much more useful tool.
What correlation is measuring
In the context of a strategy portfolio, correlation typically describes how closely two strategies’ returns have moved together over some historical period. A correlation close to +1 means the two return streams have tended to rise and fall together. A correlation close to -1 means they have tended to move in opposite directions. A correlation close to 0 means their movements have shown little consistent relationship, historically.
Most portfolio tools look at this pairwise — strategy A against strategy B, strategy A against strategy C, and so on — because that is the practical unit of comparison. A portfolio’s overall diversification is, in effect, a summary of many of these pairwise relationships at once.
Why low historical correlation is genuinely useful
When two strategies have shown low or negative correlation over a meaningful history, it suggests they have tended to respond to different conditions, or to the same conditions in different ways. That is exactly the kind of behavioural difference that supports a smoother combined equity curve — one strategy’s quiet or losing periods have historically coincided less often with the other’s. This is a real, useful signal, and it is one of the more accessible ways to compare candidate strategies before combining them.
What it doesn’t tell you
Three limitations are worth holding in mind at the same time:
- Correlation is historical, not fixed. A relationship measured over the last few years describes the past. It can shift as market conditions, volatility regimes, or the strategies’ own behaviour change.
- Correlation tends to rise in stress periods. This is one of the more consistent patterns across markets: many previously unrelated instruments and strategies can start moving together during sharp, broad market stress, precisely when diversification matters most. A comfortable low-correlation reading measured in calmer conditions can understate how related two strategies become when it counts.
- Low correlation is not the same as complete diversification. Correlation is a single statistical summary of return co-movement. It doesn’t capture why two strategies behave differently, whether that difference is likely to persist, or whether they share a hidden dependency that simply hasn’t shown up yet in the data measured.
None of this makes correlation useless — it means correlation is one input, evaluated alongside context, rather than a single number that settles the question by itself.
Correlation is not causal
It’s worth being explicit about a common misreading: a correlation figure describes association, not cause. Two strategies showing low correlation doesn’t mean one strategy’s logic somehow causes the other to behave differently, and a period of rising correlation doesn’t mean one strategy started copying the other’s behaviour. Both are simply describing how two return series have moved relative to each other — the underlying “why” requires looking at the strategies’ actual logic, timeframe, and market dependence, which is where Diversification in Algorithmic Trading Is More Than Different Markets picks up the thread.
Behaviour and context still matter
A practical habit worth adopting: treat correlation as a check, not a design principle. Build candidate combinations based on genuine behavioural differences — different entry logic, different timeframes, different market dependence — and then use correlation as one piece of evidence that those differences actually showed up in how the strategies performed historically. If two strategies you expected to behave differently turn out to be highly correlated, that’s useful information worth investigating, not a number to simply average away.
Where this fits in the SIPS workflow
Portfolio Analysis reports a portfolio’s diversification across several real dimensions rather than a single correlation figure, precisely because no single number is treated as a complete answer inside SIPS. The intent is the same one described here — correlation and diversification measures are read together, as evidence to weigh, not a pass/fail test.
The practical takeaway
Correlation is a genuinely useful tool for spotting relationships you might otherwise miss, and a poor tool for declaring a portfolio safe. Read it as historical evidence of how two strategies have related to each other so far — evidence that can and does change, especially under stress — rather than a fixed property of the strategies themselves.