
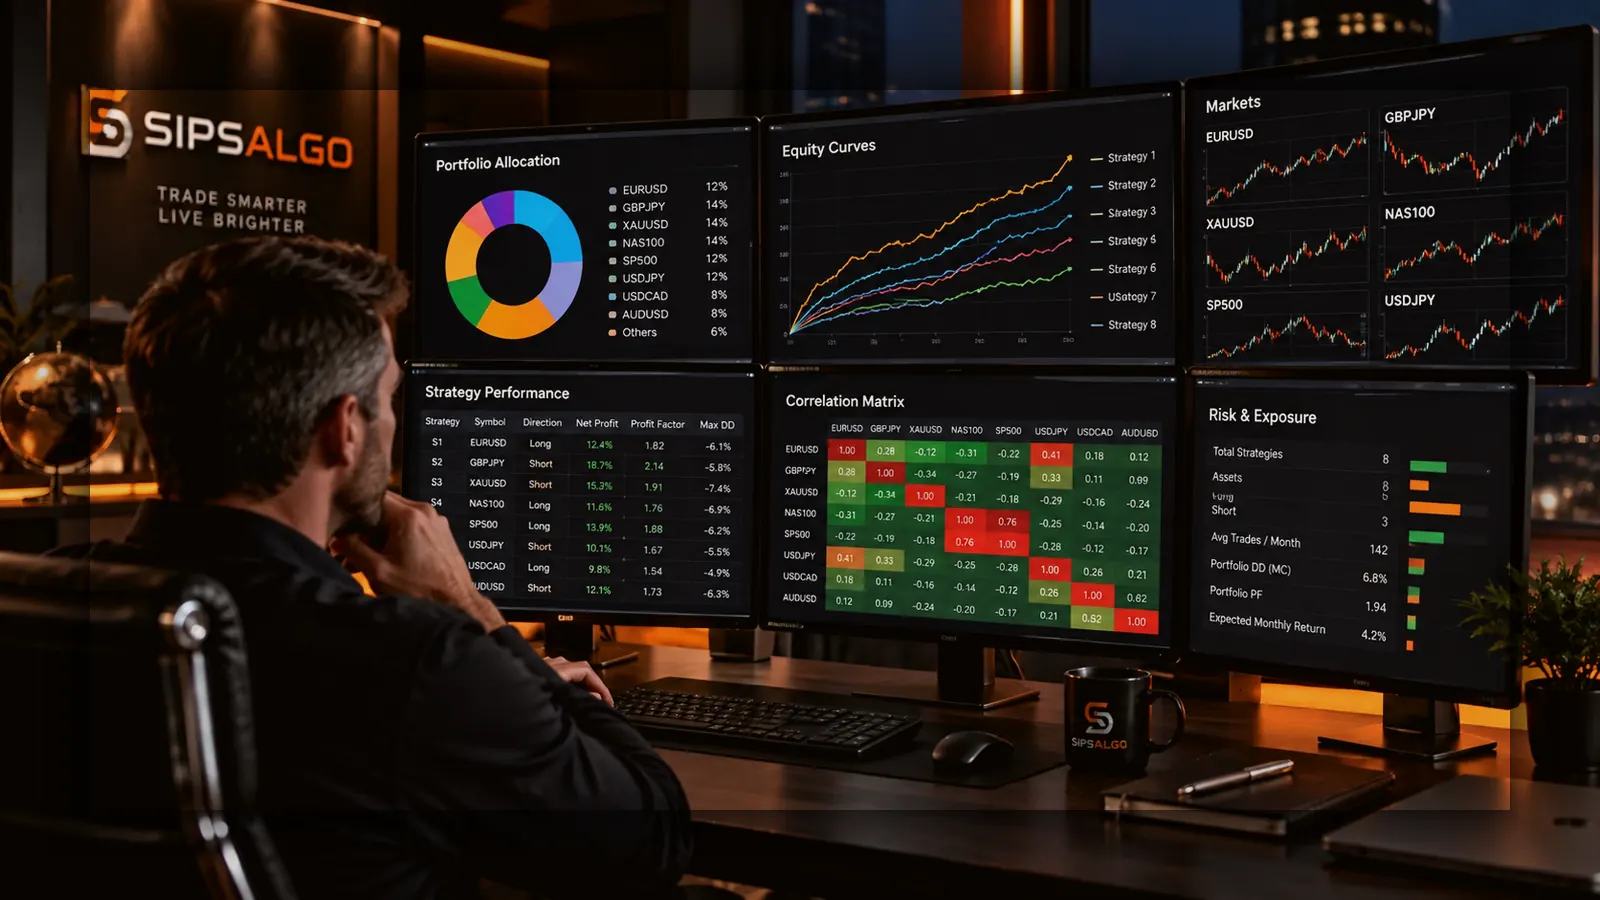
Knowing that diversification matters is one thing. Actually building a portfolio that has it is another. This is a practical framework for going from a library of individually credible strategies to a combination that has been genuinely checked for the behavioural differences that support real diversification — not just assumed to have them.
1. Start with individually credible strategies
Portfolio construction is not a substitute for strategy quality — it’s a second layer on top of it. Before a strategy is worth considering for a portfolio, it should already hold up reasonably well on its own: a sensible sample size, an acceptable Return-to-Drawdown, no obvious signs of curve fitting. See Profit Factor, Expectancy, Stability and Trade Count for how to read these measures together rather than in isolation.
2. Map market, timeframe and direction across the library
Before diving into correlation numbers, it helps to simply lay out what you have: which markets, which timeframes, which direction bias, which broad style of entry and exit. This step alone often reveals obvious gaps — a library that is entirely long-biased trend followers on major forex pairs, for example, no matter how many individual strategies it contains.
3. Examine correlation between serious candidates
Once you have a shortlist that looks behaviourally varied on paper, check how their historical returns have actually moved relative to each other. Low or negative historical correlation between two credible candidates is a good sign that the variety you designed for actually showed up in practice. See Correlation in Algorithmic Portfolios for what this measure can and can’t tell you on its own.
4. Look at behaviour, not just statistics
Numbers alone can mislead, especially over a limited sample. It helps to understand qualitatively what each strategy is actually doing — its trading style, its typical entry trigger, how it manages an open trade, how it exits. Two strategies with a similar correlation reading can still be different enough in behaviour that you’d expect their relationship to hold up better going forward than a purely statistical match.
5. Combine and recalculate at the portfolio level
This is the step that is easiest to skip and most important not to. Once you have a candidate combination, calculate its metrics as a combined portfolio — combined equity curve, combined drawdown, combined Return/DD — rather than relying on the individual strategies’ own numbers. This is where overlap and hidden concentration actually become visible; see Why the Best Individual Strategies Don’t Always Build the Best Portfolio.
6. Stress test the result
A single historical equity curve is one realised path through history. Testing how a candidate portfolio might have behaved across a wider range of plausible sequences — rather than trusting the one sequence that actually happened — gives a more honest picture of the drawdown and return uncertainty involved. Monte Carlo Testing Explained covers this idea and its limits.
7. Compare candidates side by side
Rarely is there one obviously correct portfolio. Building two or three credible candidate combinations and comparing them directly — on combined metrics, diversification mix, and robustness — tends to surface trade-offs that aren’t visible when evaluating one candidate in isolation.
8. Monitor once live
Construction doesn’t end at deployment. A backtest describes the past; live trading is a new, ongoing test of the same assumptions. Comparing live behaviour against historical expectation — evenly, without overreacting to short-term noise — is covered in How to Tell When a Live EA Is Behaving Differently From Its History.
What this framework deliberately leaves out
This is a description of the questions worth asking, not a formula for answering them automatically. The actual work of searching a large strategy library for combinations that satisfy diversification, quality and risk rules at scale is a non-trivial optimisation problem, and the exact methods used to do that well are not something this article gets into — the goal here is to explain why each step matters, not to hand over an implementation.
Where this fits in the SIPS workflow
Portfolio Builder runs this kind of search across a qualified strategy library automatically, and Custom Builder lets you assemble and check a hand-picked combination against the same combined-metric and validation logic. Portfolio Analysis is where the “stress test and compare” steps above become concrete, real numbers for a specific candidate.
The practical takeaway
Diversification is built through a sequence of checks, not a single decision. Start with individually sound strategies, map their variety honestly, verify that variety with correlation and behaviour, then confirm the whole thing works as a combination — not just as a list of good ingredients.