
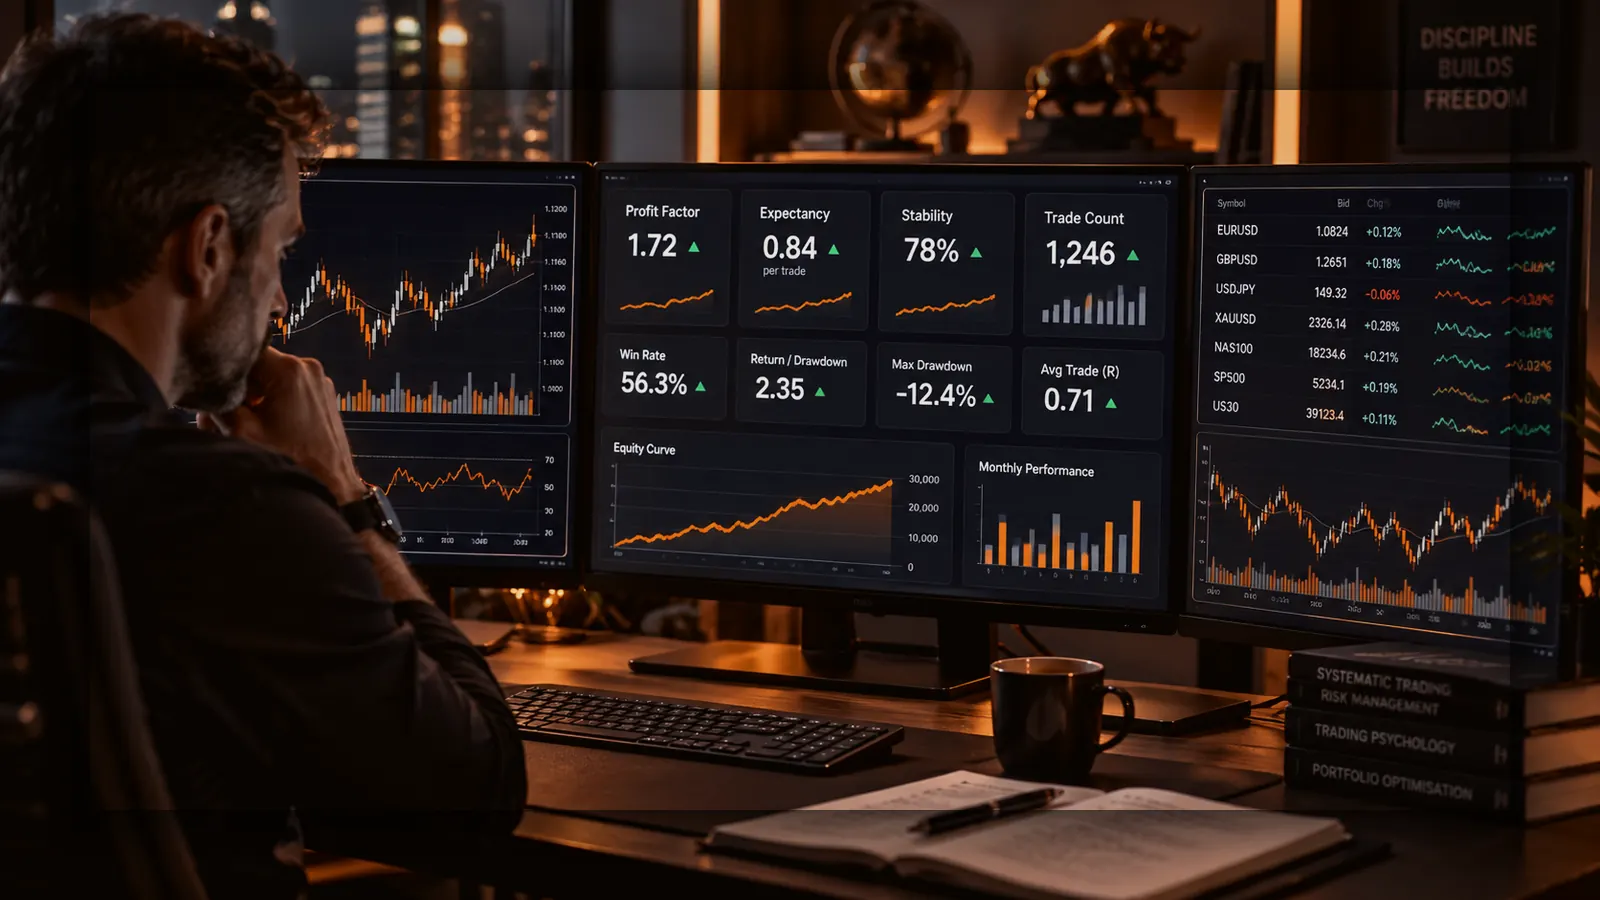
It’s common to see a strategy judged on a single headline number — usually Profit Factor, sometimes win rate. Each of these metrics is genuinely informative, and each of them can be misleading when it’s the only thing you look at. Reading them together, as a set, gives a far more honest picture than any one of them alone.
Profit Factor
Profit Factor is gross profit divided by gross loss. A Profit Factor above 1.0 means the strategy made more than it lost over the period tested; below 1.0 means the opposite. It’s a useful, compact summary — but it says nothing about how many trades produced that result, how volatile the path to it was, or how the wins and losses were actually distributed. A Profit Factor of 1.8 built from 15 trades and one built from 800 trades are not comparable in reliability, even though the ratio looks identical.
Expectancy
Expectancy is the average expected profit or loss per trade — a way of expressing “what does a typical trade from this strategy tend to look like?” It complements Profit Factor by putting the result on a per-trade basis rather than a cumulative one, which can be more intuitive for thinking about position sizing and risk per trade. Like Profit Factor, it is a historical average, not a promise about the next trade.
Stability
Stability describes how consistent a strategy’s equity growth has been — broadly, how smoothly the equity curve has climbed rather than lurching between sharp gains and sharp setbacks. A strategy can have a strong Profit Factor while being highly unstable, if its profit is concentrated in a small number of large winning trades surrounded by a long, choppy stretch of smaller losses. Stability helps surface that pattern, which Profit Factor alone would not.
Trade count (sample size)
Every metric above is a statistical estimate, and every statistical estimate is more trustworthy with a larger sample. A strategy with a handful of trades can show an excellent Profit Factor purely by chance — a small number of favourable trades can dominate the ratio in a way that a larger, more representative sample would smooth out. There is no single universal minimum trade count that makes a result trustworthy; more is generally better, and a very small sample deserves proportionally more scepticism, whatever the headline numbers say.
Win rate — useful, but easy to over-read
Win rate is simply the percentage of trades that were profitable. It feels intuitive, but a high win rate doesn’t necessarily mean a good strategy, and a low win rate doesn’t necessarily mean a bad one. A strategy can have a 30% win rate and be strongly profitable, if its winning trades are, on average, large enough relative to its losing trades. Win rate is worth reading alongside average win size and average loss size, not as a standalone verdict.
Return-to-Drawdown
Return/DD puts return in context against the drawdown endured to achieve it — a strategy that made good money while enduring a punishing drawdown is a different proposition from one that made similar money more smoothly. See Return-to-Drawdown: Why Profit Alone Can Mislead for a closer look at this specific relationship.
Why one attractive number shouldn’t dominate the decision
The practical risk of focusing on a single metric is that it’s easy, even unintentionally, to find a strategy that looks exceptional on that one measure and weak everywhere else — a strategy with a phenomenal Profit Factor built on very few trades, for instance, or a high win rate propped up by one enormous loss waiting to happen. Reading several metrics together, and checking that they broadly tell a consistent story, is a simple but effective defence against being misled by whichever number happens to look most impressive.
Where this fits in the SIPS workflow
Strategy Metrics Explained defines every one of these measures in the exact terms used throughout SIPS, and Strategy Performance presents them together for a given strategy, alongside its full sample and time-series detail, rather than surfacing any single figure as the headline verdict.
The practical takeaway
No single metric tells the whole story, and every metric can be made to look good in isolation if you search hard enough for the strategy that happens to score well on it. The discipline worth building is reading Profit Factor, Expectancy, Stability, trade count and Return/DD together, and treating disagreement between them — a great Profit Factor with a tiny sample, say — as a signal worth investigating rather than a detail to skip past.