
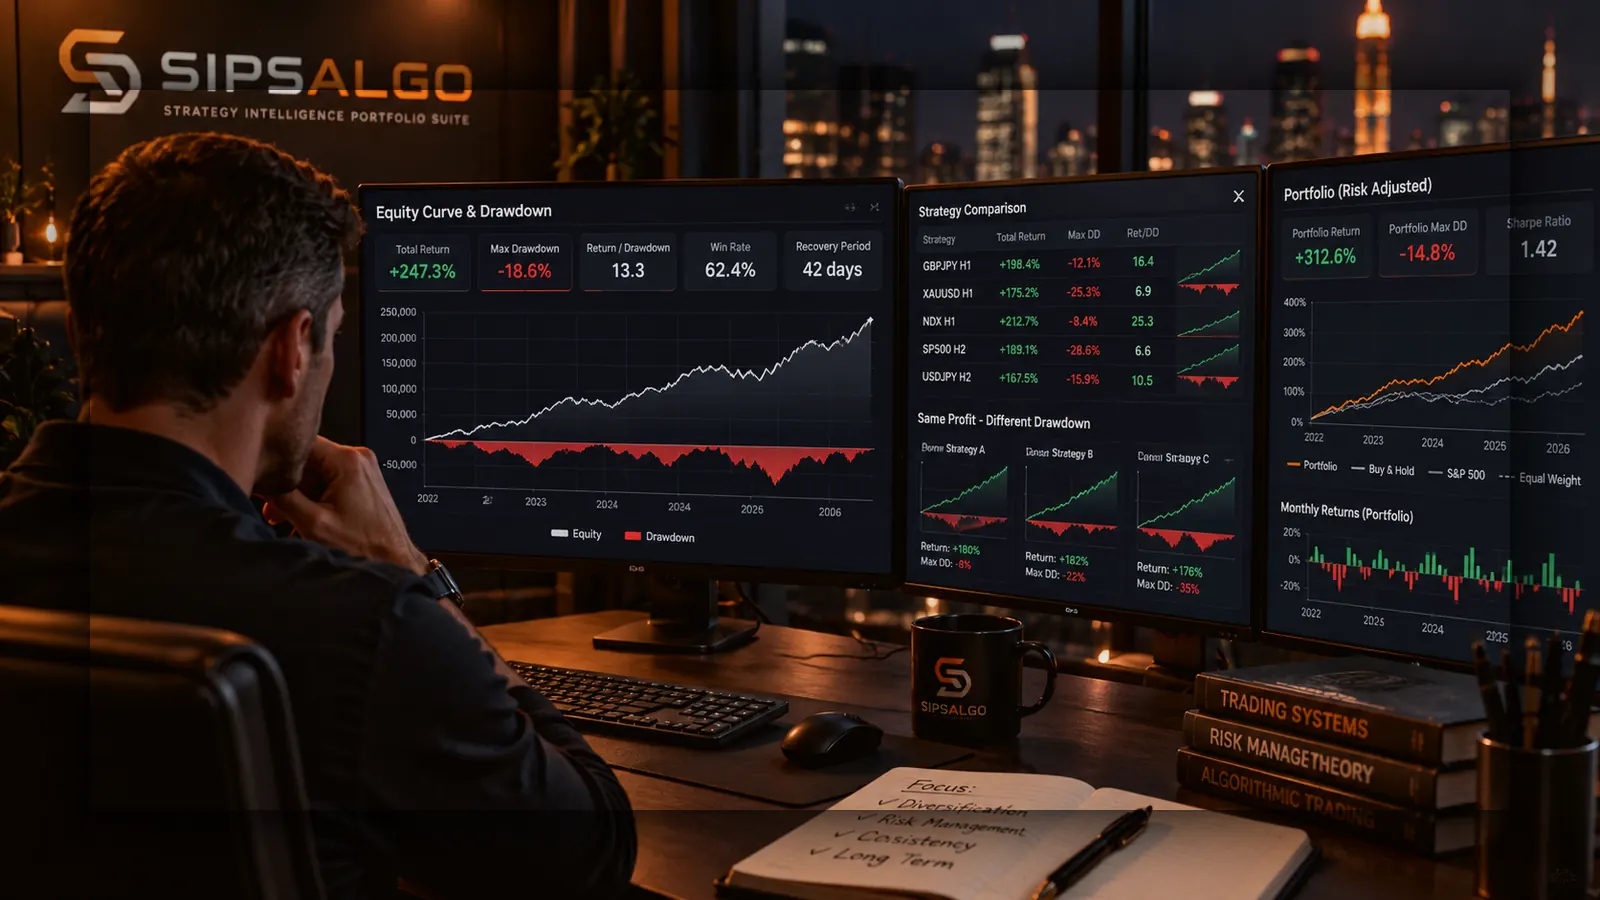
Net profit is the number that catches the eye first, and it’s often the least useful number on its own. Two strategies can post a similar net return over the same period and represent completely different experiences to actually trade, because return alone says nothing about the path taken to get there. Return only becomes meaningful once it’s read next to drawdown.
Why the path matters as much as the destination
Imagine two strategies, as an illustrative example: Strategy A returns 40% over a year with a maximum drawdown of 10%. Strategy B also returns 40% over the same year, but with a maximum drawdown of 35%. Both arrived at the same destination. The journeys were not remotely comparable. Strategy B spent meaningful stretches of the year deep underwater, tying up far more capital efficiency and putting far more psychological pressure on anyone watching the account, for an identical end result.
Return-to-drawdown (often written Return/DD) is a simple way of putting these two figures in the same frame: return achieved relative to the drawdown endured to achieve it. Higher generally indicates a more capital-efficient result — more return for a given amount of pain along the way.
Why this matters beyond comfort
This isn’t only about psychological comfort, though that matters too — a strategy nobody can tolerate holding through its own drawdown is a strategy that tends to get abandoned at exactly the wrong moment, which is its own kind of risk (see The Psychology of System Trading). It also matters mechanically: a deeper drawdown means a larger recovery is required just to get back to even, and capital sitting through a large drawdown is capital that isn’t available for anything else in the meantime.
Return/DD at the portfolio level
The same principle applies at the portfolio level, and arguably matters more there, because portfolio-level drawdown is not simply the average of its member strategies’ individual drawdowns — see Why Portfolio Drawdown Can Matter More Than Individual Strategy Drawdown. A portfolio built from strategies with strong individual Return/DD figures can still produce a disappointing combined Return/DD if those strategies’ drawdown periods happen to overlap in time. Checking a portfolio’s own combined Return/DD, rather than assuming it inherits the average of its members’ figures, is one of the more important portfolio-level checks available.
Why there’s no universal “good” number here
It’s tempting to want a single benchmark — “a Return/DD above X is good” — but that kind of threshold depends heavily on context: the strategy’s trade frequency, the trader’s own risk tolerance, the account’s purpose, and the broader portfolio it sits within. A number that looks unremarkable for a slow, low-frequency strategy might be a strong result for a fast, high-frequency one, and vice versa. This article intentionally doesn’t prescribe a specific threshold, because doing so without solid supporting evidence would be more misleading than useful. Read Return/DD comparatively — against other candidates being considered for the same portfolio — rather than against a fixed external bar.
Reading Return/DD alongside other metrics
Return/DD is a genuinely useful summary, but it’s still a summary — it compresses an entire equity curve into one ratio, and two very different equity paths can produce a similar figure. It works best read alongside the strategy’s other metrics (Profit Factor, Expectancy, Stability, trade count — see Profit Factor, Expectancy, Stability and Trade Count) rather than in isolation, and alongside a visual look at the equity curve itself, which can reveal whether the drawdown was one sharp event or a long, grinding stretch.
Where this fits in the SIPS workflow
Return/DD is shown throughout SIPS at both the strategy level (Strategy Metrics Explained) and the portfolio level (Portfolio Analysis), calculated from the genuine combined-portfolio trade stream at the portfolio level rather than derived from member averages — consistent with the combined-metric approach described throughout this series.
The practical takeaway
Net profit answers “how much,” and stops there. Return-to-drawdown starts to answer “at what cost,” which is usually the more important question for anyone who actually has to hold the position through the drawdown, not just admire the final number afterward.